When most people hear the phrase financial independence, they probably think about retirement. Perhaps it’s the point at which you have accumulated enough money that you no longer need to work. You hand in your notice, say goodbye to your colleagues and never have to worry about earning another pound again.
And while that can certainly be one version of financial independence, I don’t think it has to be the definition. In fact, I think financial independence can be much more useful when you think about it as having choice, rather than simply having stopped working.
Financial independence is really about reaching a point where your finances give you options. You might still want to work. You might enjoy your job, like the people you work with or simply enjoy having something that gives your week structure and purpose. But there is a big difference between working because you want to and working because you have to.
That difference can be incredibly valuable.
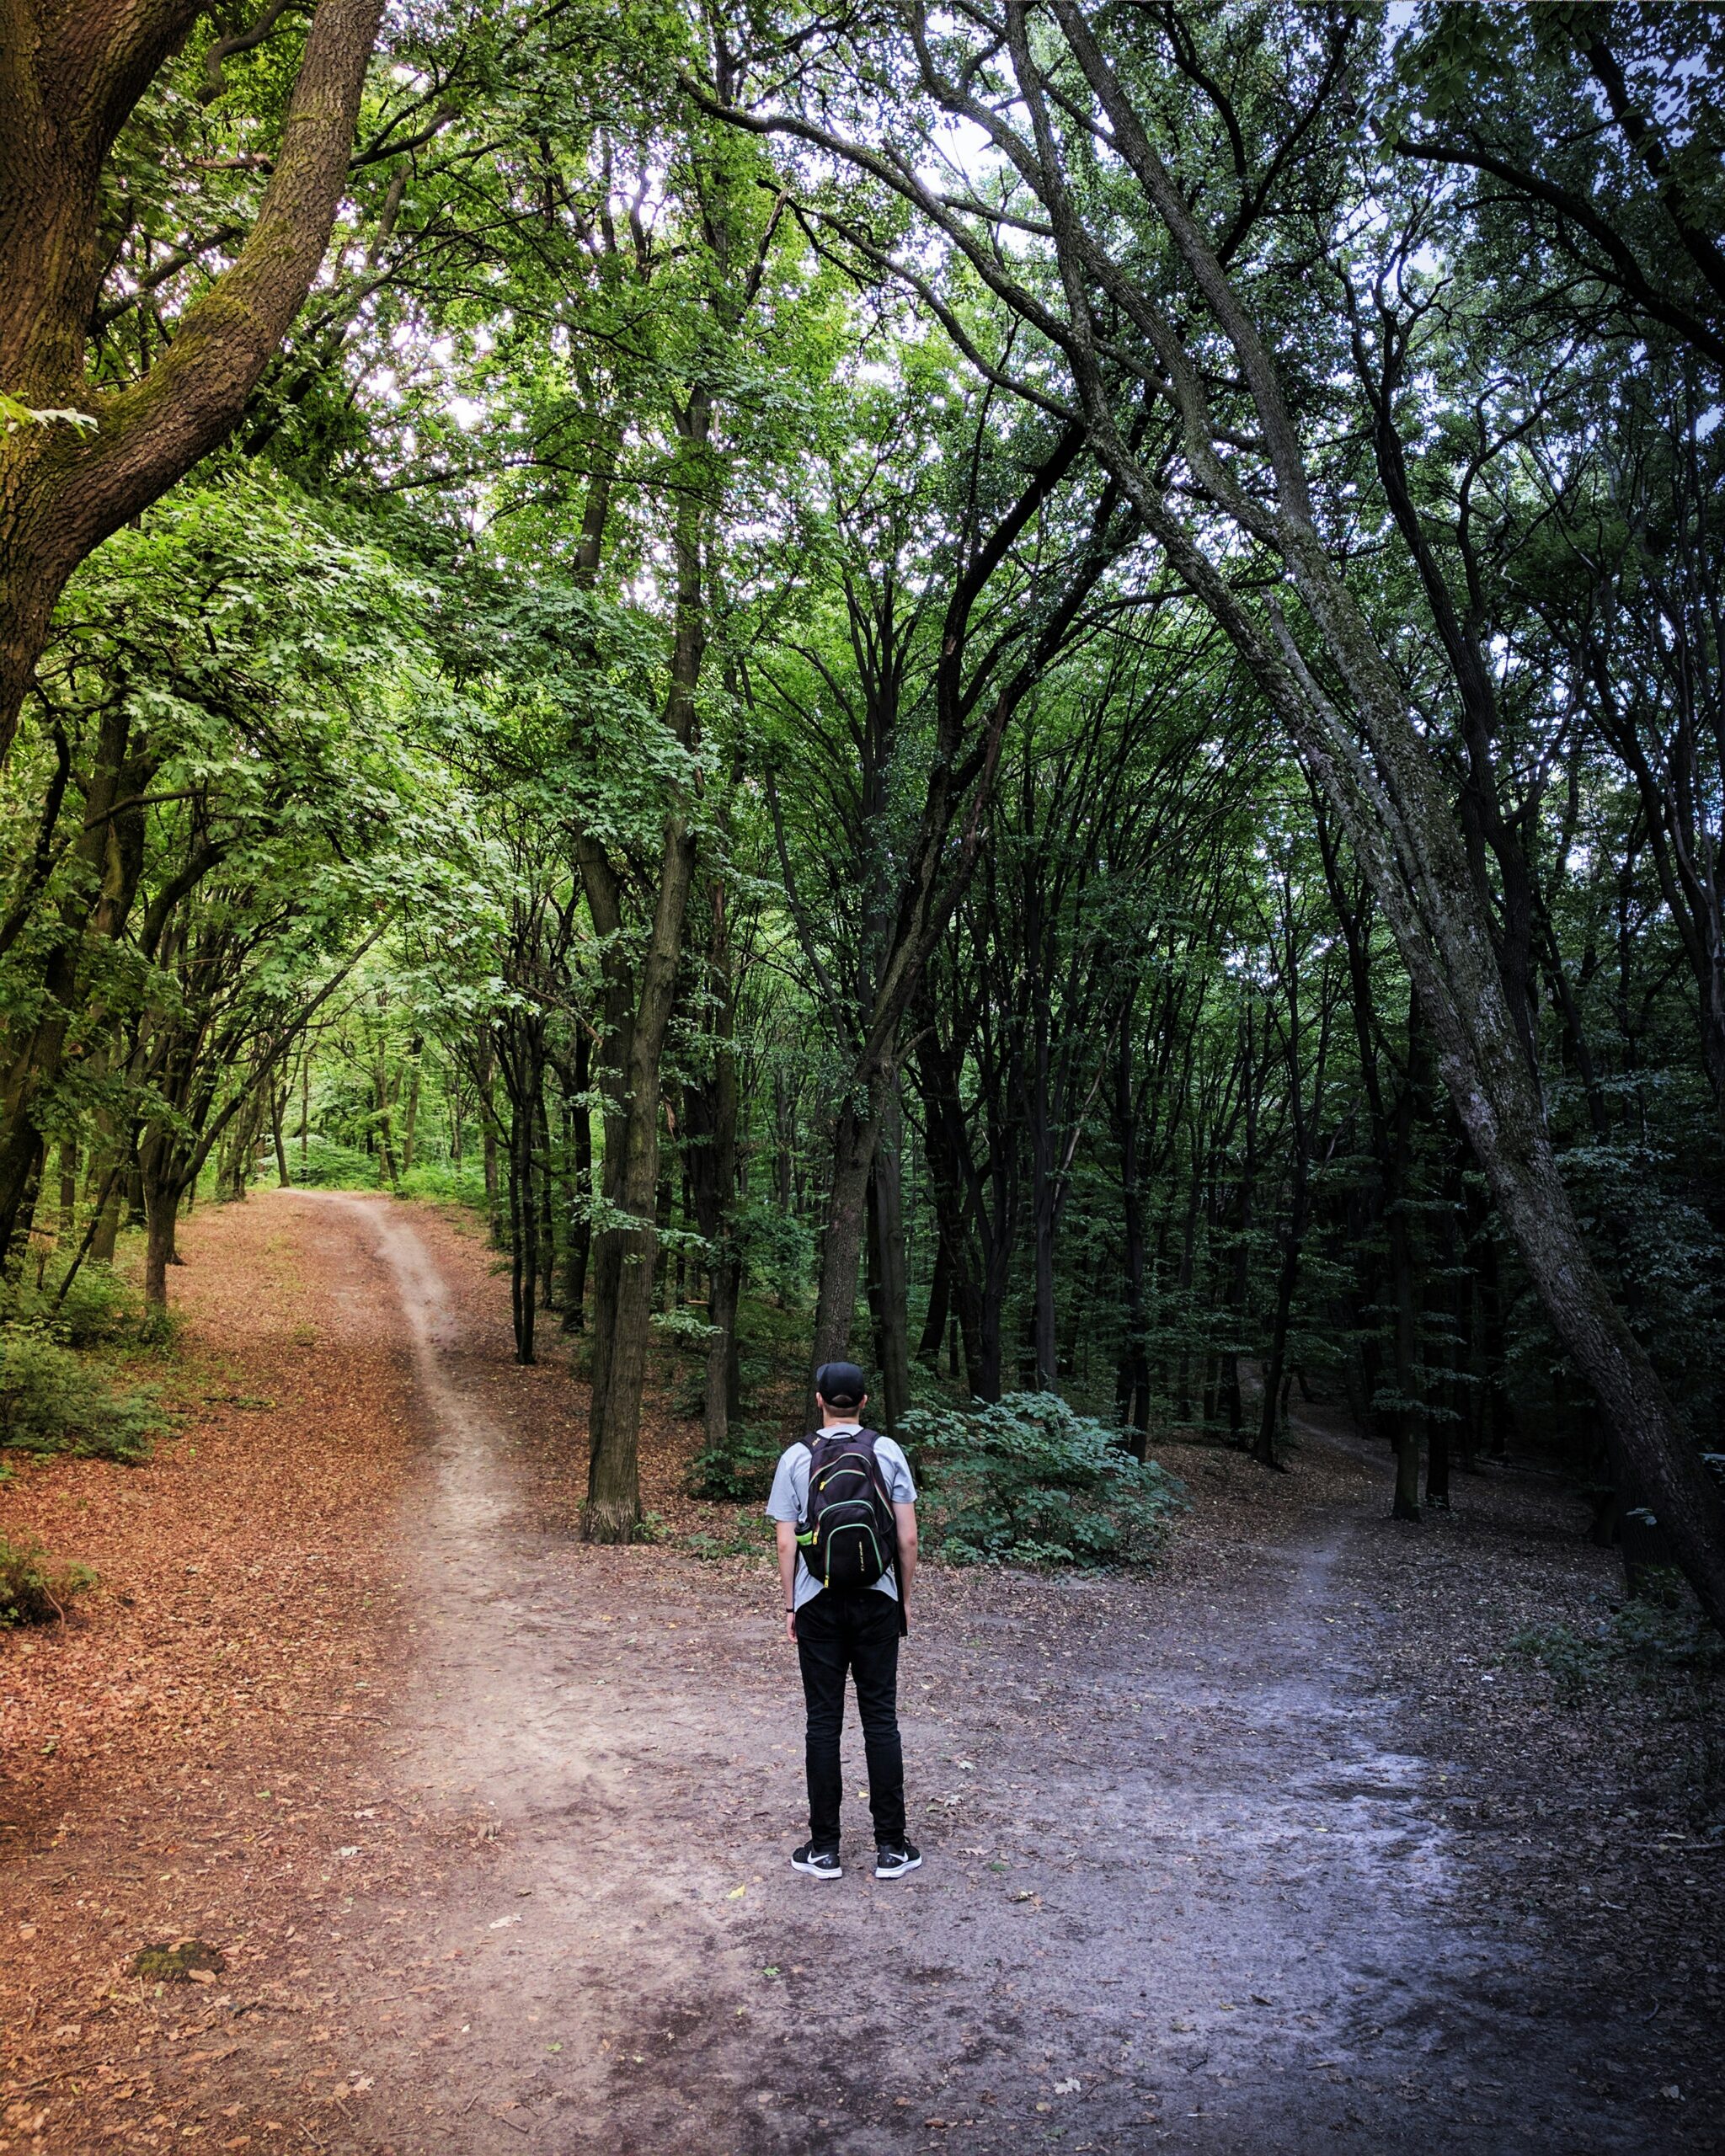
Imagine you have reached a point where you know that, if you wanted to, you could stop working and still maintain the lifestyle you enjoy. You might decide to carry on working for another five years. You might reduce your hours. You might take a year off. You might change career and do something you’ve always wanted to try, even if it pays less. I have been fortunate over the years to have seen people decide to do each of those things.
The important thing is that the decision becomes YOURS. This is one of the reasons I think financial planning is about much more than calculating whether you have enough money to retire.
A traditional retirement question might be ‘When can I afford to stop working?’. But perhaps a more interesting question is ‘When does work become a choice rather than a necessity?’. Those two questions can lead to very different conversations.
For some people, financial independence might mean retiring completely at a specific age such as 60.
For someone else, it might mean having enough financial security to move from a demanding full-time career into something more flexible.
For another person, it might mean continuing to work well into their 60s or 70s because they genuinely enjoy it, but knowing they don’t need the income.
There is no right answer. And that’s the point!
Financial independence isn’t necessarily about reaching a particular age. It’s about reaching a financial position that gives you the freedom to make decisions based on what you want your life to look like, rather than what your finances dictate.
It can also change the way you think about saving. When you’re working towards a distant retirement, it can be tempting to think that life starts later. Save now, work now, invest now and eventually you will get to enjoy the money you’ve accumulated.
But financial independence can bring some of that freedom forward. Perhaps reaching a certain level of financial security means you can take the family on the holiday you’ve been putting off. Maybe you can help your children when they need it. Perhaps you can reduce your working hours while you’re still young enough to enjoy the extra time. Or maybe you can simply stop worrying quite so much about what would happen if your circumstances changed.
None of these things necessarily require you to retire. They require you to have enough financial security to make choices. This is also why I think the idea of a single retirement number can be misleading. There isn’t one amount of money that means someone is financially independent. It depends on the life you want to live.
What does that life cost? What income will you have? What flexibility do you want? How much do you want to spend today? What might you want to spend in the future? And how much security do you want to build in?
Once you start answering those questions, financial independence becomes much more personal. It stops being about chasing a particular pension pot and starts being about understanding what your money needs to do for you.
Perhaps that’s the biggest benefit of financial independence. It’s not necessarily the ability to retire, it’s the ability to choose.
Please note, a pension is a long-term investment not normally accessible until 55 (57 from
April 2028). Your capital is at risk. The fund value may fluctuate and can go down, which
would have an impact on the level of pension benefits available.
This article is for general information only and does not constitute advice. The information contained within this article was accurate at the date of publication and is subject to change.

 Production